Autumn Budget 2026: What Does It Really Mean for Hackney and East London’s Property Market?
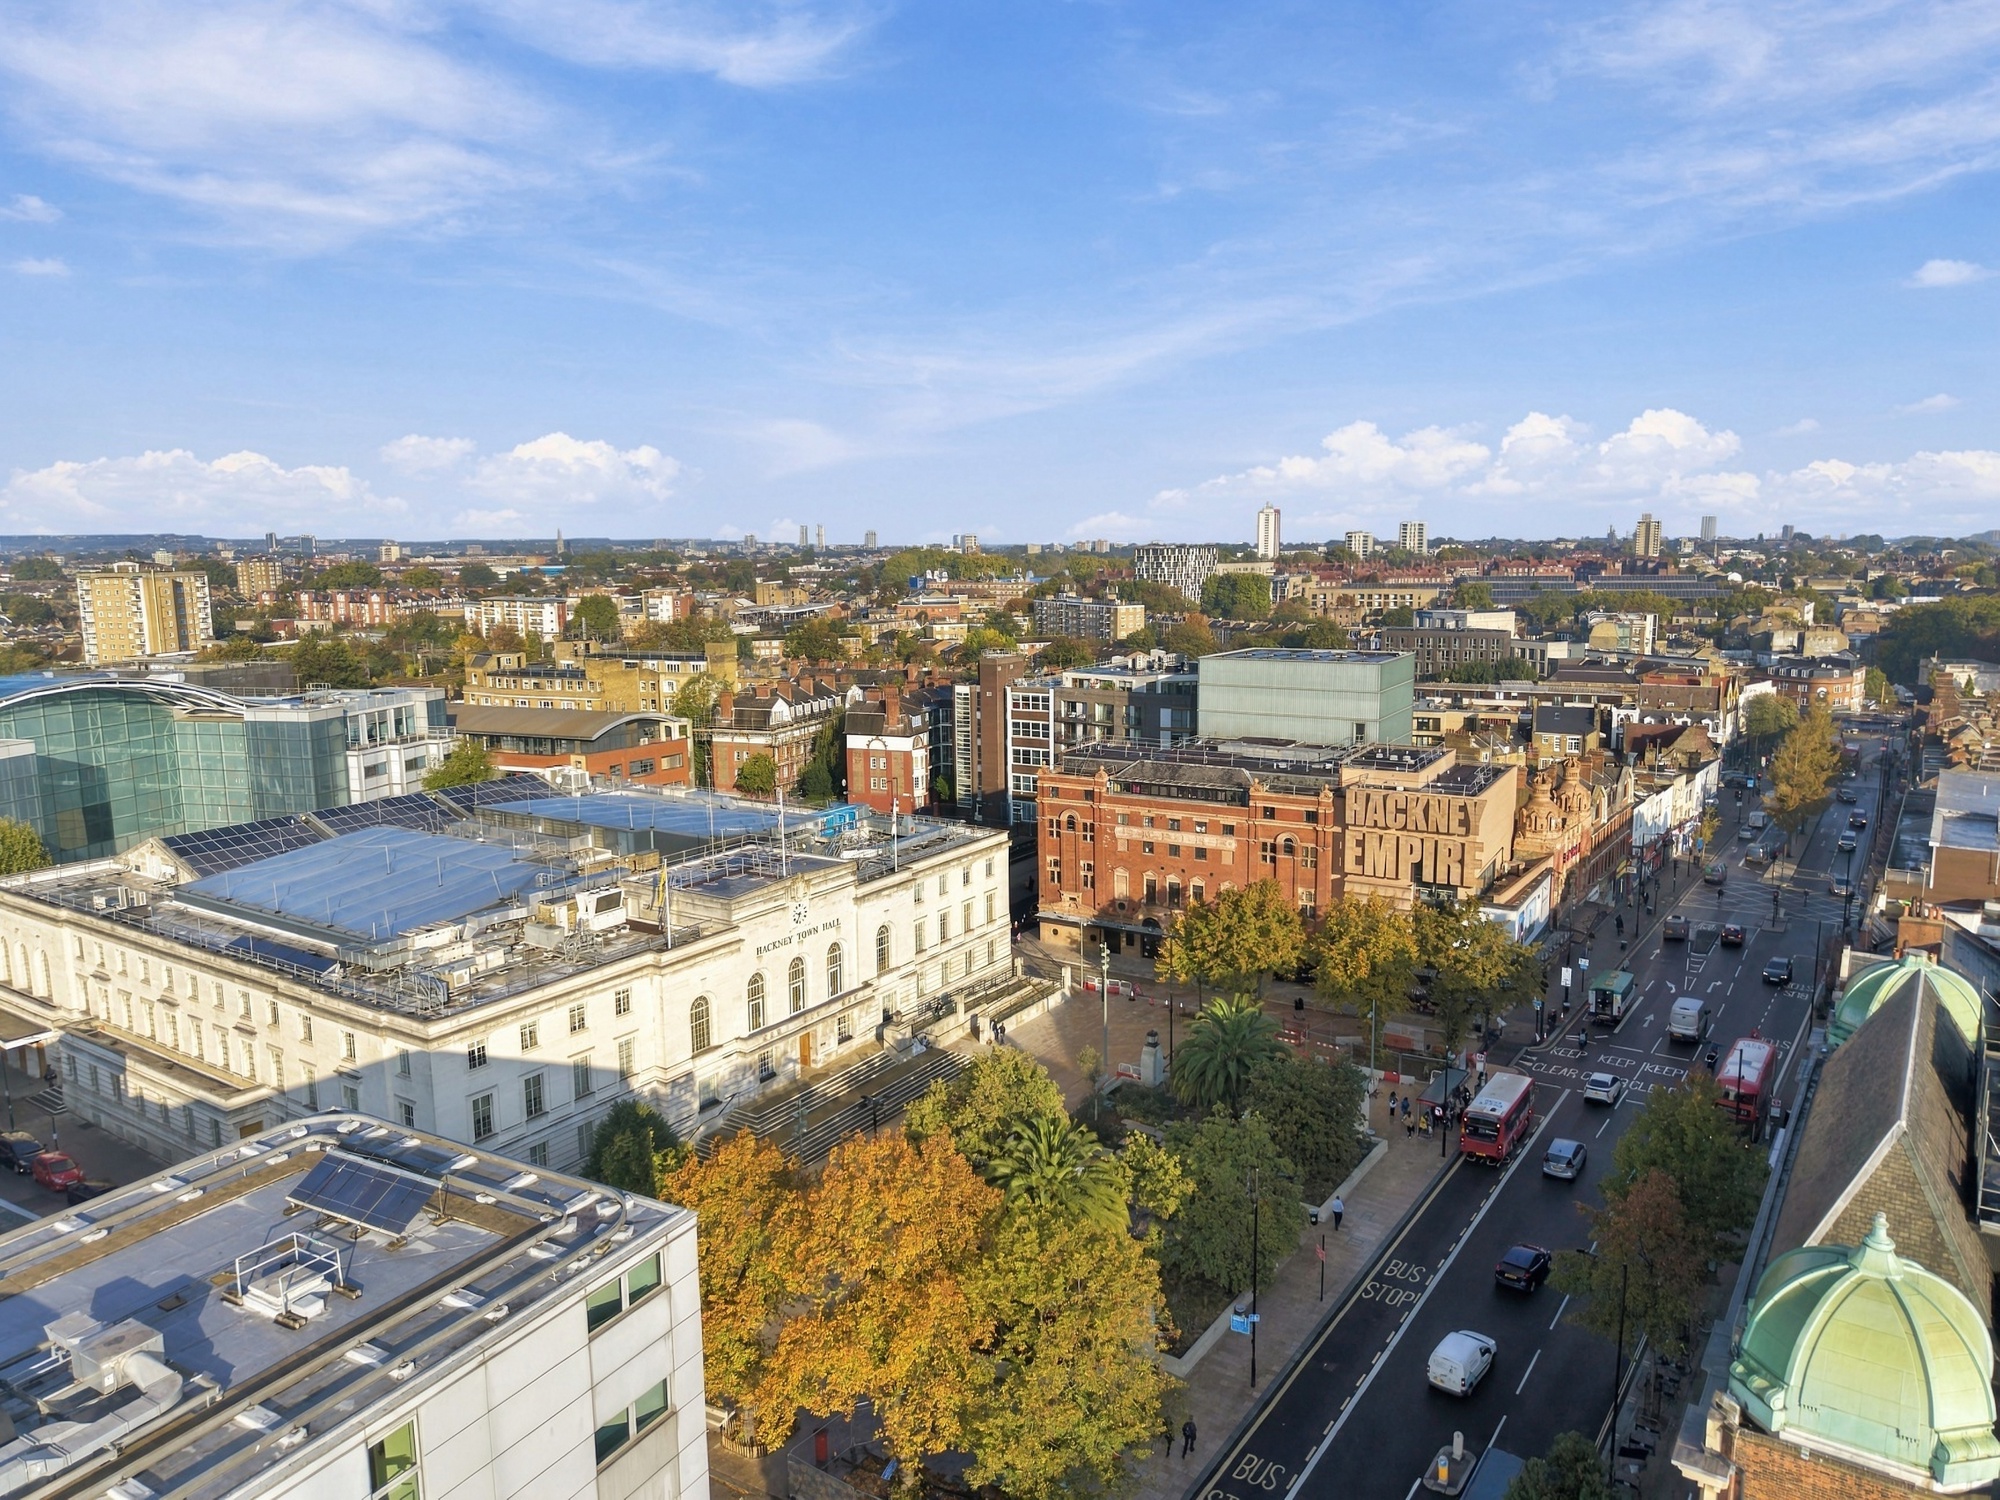
The Autumn Budget 2026 has given the property market plenty to talk about. A new scheme allowing first-time buyers to purchase with just a 2.5% deposit, further tax increases for landlords and additional taxes on banks.
On paper, some of these announcements sound fantastic. But I’ve worked in estate agency long enough to know that what sounds good in a government announcement doesn’t always translate into a good deal for the consumer.
And while everyone is discussing government schemes, I think we’re overlooking something important: we’re in a buyer’s market, but that doesn’t mean it’s a bad time to sell. Here’s my take on the Budget and what it means for Hackney, Homerton, Dalston, Bow, Stratford and the wider East London property market.
Your First Home: A 2.5% deposit sounds fantastic, but what’s the catch?
The government’s Your First Home scheme is intended to help around 70,000 first-time buyers purchase qualifying new-build properties. Eligible purchasers could put down just 2.5%, supported by a government equity loan worth 20% of the property price. The stated inner London property cap is £650,000, with a London household income limit of £140,000. Applications are expected from February 2027, with initial loans from April.
Sounds brilliant, doesn’t it? Well, I’m not entirely convinced.
New builds can be a bit like buying a brand-new car.
You’re often paying a premium for something shiny and new. There’s the immaculate marketing suite, the pristine finishes and perhaps a few incentives thrown in. But once you move in, you’re no longer selling a brand-new property. You’re competing with the resale market, potentially against near-identical apartments in the same development. That new-build premium doesn’t necessarily carry over.
Now imagine buying with just a 2.5% deposit. There’s very little initial equity to cushion a fall in value. If you need to sell early, you could find yourself in negative equity or needing to put money towards the sale, especially once estate agency and solicitor costs are considered. The government’s equity share also needs to be settled.
Imagine having to put your hand in your pocket just to sell your own home.
And I can’t help wondering whether encouraging buyers specifically towards new developments also serves another purpose: helping developers shift stock. Is that a deliberate ploy? I can’t say it is. But when support is restricted to new builds, it’s a fair question to ask who else benefits besides the buyer.
The government loan is interest-free for five years, but it isn’t free money. It must be repaid, generally based on the relevant percentage of the property’s value when repaid. If values rise, the repayment can rise too. Over the long term, buyers may benefit from capital appreciation and reducing their mortgage balances, subject to market conditions. I’m not saying the scheme is wrong for everybody; I am saying buyers should examine the resale market and the full costs before being sold on the low deposit.
There’s a difference between making a property easier to buy and making it a good investment.
Buying versus renting in East London: Are tenants overlooking an opportunity?
With rents remaining high across Hackney, Bow, Stratford and Canary Wharf, I’d encourage more tenants to compare what they’re paying in rent with the cost of purchasing. Let’s take someone paying £2,500 a month and considering a £450,000 home, on an illustrative 30-year repayment mortgage at 5%.
| Cost | Standard purchase | Your First Home |
|---|---|---|
| Property price | £450,000 | £450,000 |
| Deposit | £40,000 | £11,250 |
| Government equity loan | £0 | £90,000 |
| Mortgage required | £410,000 | £348,750 |
| Monthly repayment | £2,201 | £1,872 |
| Compared with £2,500 rent | £299 less | £628 less |
These mortgage figures are illustrative and exclude service charges, maintenance, buildings insurance and other ownership costs. They do not account for future mortgage-rate changes or interest on the equity loan after year five.
How much would you actually need saved?
For an eligible first-time buyer purchasing at £450,000, stamp duty would be £7,500. If you allow £3,000-£5,000 for legal fees, surveys, mortgage fees and moving costs, a standard purchase with a £40,000 deposit requires approximately £50,500-£52,500 saved. Under Your First Home, with an £11,250 deposit, it’s approximately £21,750-£23,750. Both exclude an emergency cash buffer.
A £90,000 government equity loan could also attract approximately £113 a month in interest in year six and £225 a month from year seven under the illustrated structure, assuming the loan remains outstanding. Those interest payments do not pay down the equity loan.
If you’re spending £30,000 a year in rent, surely it is worth checking whether buying could make sense? Ownership isn’t for everybody, but I think some tenants dismiss it without ever looking at the numbers.
Landlords are being squeezed again. Will tenants pay the price?
The announced property income tax rates from April 2027 are 24% for basic-rate taxpayers, 44% for higher-rate taxpayers and 49% for additional-rate taxpayers.
This is on top of the pressure from mortgage costs, service charges, maintenance, insurance and changing rental regulation. I understand the argument that landlords should pay their fair share, but I question whether making investment less attractive really helps tenants.
Some landlords will sell. Others will look to increase rents.
Where rental properties are sold to owner-occupiers, private rental supply can shrink. If demand holds up, that could create further pressure on rents. Landlords cannot simply raise rents as much as they please: affordability, local competition and tenancy rules matter. But it’s unrealistic to assume that higher costs can never reach tenants.
You can increase taxes on landlords, but you can’t assume the financial consequences will stop with them.
For landlords in Hackney, Homerton, Bow, Mile End or Stratford, now is a sensible moment to revisit rental yield, costs and the property’s potential sales value. For some, keeping the investment still makes sense; for others, a sale might release capital for a different opportunity.
Higher taxes on banks: Will consumers pick up the bill?
The Budget also announced that the bank corporation tax surcharge would temporarily increase from 3% to 6% for 15 months from January 2027. It makes for an appealing headline. Who doesn’t like the sound of banks paying more tax?
But banks aren’t charities. They have shareholders and margins to protect. Some could seek to recover costs through mortgage product fees, lending margins or other charges. That isn’t a prediction that mortgage rates must rise: funding costs, swap rates and lender competition are major drivers. It’s simply worth asking whether some of the bill could ultimately fall on customers.
It’s optimistic to assume banks will just accept lower profits without considering whether costs can be passed on.
Are Hackney house prices falling? The answer depends on the property
Zoopla’s October 2026 House Price Index reported 7% more homes available for sale across the UK than a year earlier, while sales agreed were 7% lower. London average prices were approximately 1% lower year on year. But those are broad figures, not a valuation of your street.
A period house near Victoria Park, a converted flat in London Fields and a modern apartment in Hackney Wick can behave very differently. There is more stock competing for buyers, and that makes the asking price, presentation and choice of estate agent particularly important.
Is now a bad time to sell a property in Hackney? Absolutely not
I don’t want all the negative property headlines to put homeowners off moving when they have good reasons to do so. Buyers still relocate, have children, downsize, separate or move for work. They are simply more selective now.
At Livco, we recently handled the sale of a period conversion on Grove Road, close to Victoria Park, which attracted 18 viewings and sold above its asking price. That’s hardly evidence of a market where nobody wants to buy.
There are still buyers willing to compete for the right property.
The difference is that you have to give them a reason. Professional photography, a realistic valuation, proactive applicant management and the ability to position the property against competing homes matter far more than they did when the market was rising quickly. It’s a good market for sellers who take the process seriously.
Selling for less could actually mean buying for less
This is one of the most overlooked opportunities for homeowners moving up the property ladder. Say your Hackney flat is worth £450,000 today, but you think it might have achieved £475,000 a few years ago. That £25,000 difference understandably stings.
But suppose the house you want to buy is now £750,000 rather than £800,000. You’re receiving £25,000 less, yet spending £50,000 less on your onward purchase. The difference between the two prices has improved by £25,000, before transaction costs and mortgage considerations.
Your property doesn’t exist in isolation. You’re selling and buying in the same market.
This can be especially relevant for homeowners moving from flats into houses in Hackney, or considering Walthamstow, Leyton and areas further east. A softer market isn’t automatically bad news when you’re trading up.
Why choosing the right estate agent in Hackney matters
One of my frustrations with estate agency is the tendency for some agents to tell sellers what they want to hear rather than what they need to hear. Everybody enjoys a high valuation. But what use is the highest asking price if the property doesn’t sell?
In a competitive market, buyers notice when a property looks overpriced against its neighbours. Early marketing momentum is valuable, and it can be wasted by starting too high.
If you’re considering selling a property in Hackney, I’d look at an agent’s recent comparable sales, property marketing, applicant database, communication and, above all, their actual pricing strategy. At Livco we base valuations on local evidence, competing stock and what buyers are prepared to pay – not simply the figure that wins the instruction.
The aim is not the highest asking price. It’s the best achievable sale price.
Why do buyers wait until prices rise before they want to buy?
This is the part of the market that fascinates me most. Everyone wants to buy when prices are rising, the headlines are positive and five other buyers are fighting over the same home. Yet when prices soften, sellers become negotiable and buyers finally have more power, everyone suddenly wants to wait.
Some of the best opportunities in property come from going against the grain.
It doesn’t mean prices can’t fall further or that every listing represents a bargain. Condition, location, lease terms, service charges and resale prospects all matter. But I’d rather buy a good property at a sensible price in an unpopular market than overpay because everyone else suddenly thinks property is a great idea.
And for sellers, the other side of this is encouraging. There are serious buyers looking now – buyers with mortgage agreements, clear requirements and genuine motivation. You don’t necessarily need dozens of them. You need the right one.
My view on the Hackney property market heading into 2027
The Budget offers potential benefits for first-time buyers, but the tiny deposit and equity-loan structure warrant caution. Higher landlord taxes could create more sales stock while reducing rental supply in some areas. And higher taxes on banks may have knock-on effects, depending on how lenders respond.
But I don’t believe sellers should automatically put their plans on hold. There is genuine demand for homes that are priced and marketed well. Equally, buyers have more choice, and homeowners trading up may be able to negotiate a better price on their next property.
Don’t make property decisions based purely on government announcements or newspaper headlines.
Look at the numbers, understand your local market and make the decision that suits your circumstances. Property markets move in cycles. Sometimes the biggest opportunities appear when everyone else is feeling cautious.
Speak to Livco about selling or letting in East London
Livco are independent estate and letting agents covering Hackney, Homerton, Dalston, Clapton, London Fields, Hackney Wick, Bow, Mile End, Stratford, Walthamstow, Leyton and surrounding areas.
Whether you’re considering selling, buying your first home or reviewing a rental investment, we’re happy to give straightforward advice based on recent comparable sales and current local demand. Book a property valuation or discuss your options.
This article represents the author’s opinion as at 29 October 2026. Mortgage calculations are illustrative. Property values can rise or fall; individual mortgage eligibility, taxation and scheme terms vary.